24 September 2026 / 9 min read
Marine underwriting team - Global RE Underwriting
A very bumpy year
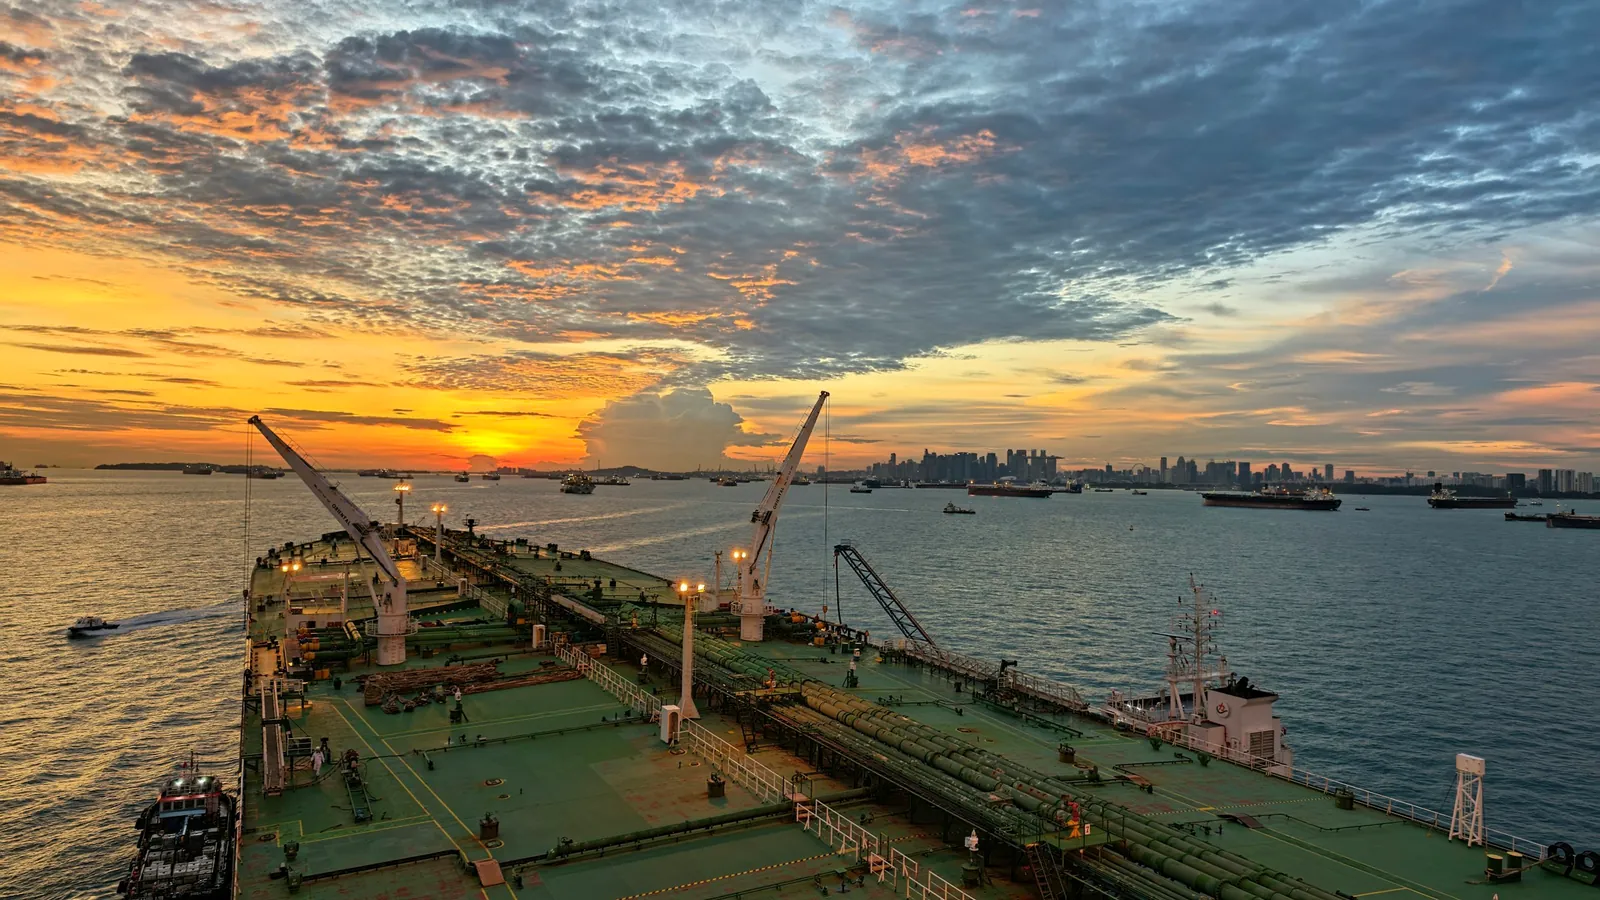
We cannot remember a class moving as quickly as marine war has this year. Additional premiums for Hormuz transits went from a small fraction of hull value to several percent within weeks of the conflict escalating in March. They eased after the June ceasefire, then jumped again in July when it fell apart. One broker described it, fairly, as a roller coaster that follows the oil price.
War extensions across the Gulf were cancelled at very short notice, and governments stepped in with guarantees and extra capacity to keep energy and trade moving. It was a good reminder of why the class matters, and of how fast private capacity can pull back when it gets frightened.
One ship, many policies
A single tanker can carry hull, cargo, loss of hire, P&I and crew exposures, often placed with different insurers who each think their share is small. In a port strike or a chokepoint incident, several of those vessels can be hit at once.
So we ask cedants to show us their listed-area exposure voyage by voyage, how they track vessels inside high-risk zones in real time, and how marine war adds up with energy and political violence business written elsewhere in the same group.
Wordings are being tested
Seven-day cancellation clauses, listed-area definitions, blocking and trapping cover, and the line between war and strikes, riots and civil commotion are all under strain. Loose language is cheap in a quiet year and very expensive when a conflict is live.
Treaty and facultative support is easiest to find where the original wordings are current, the cedant can explain how it sets additional premiums, and the event definitions in the reinsurance match the underlying policies.
Capacity is coming back, carefully
Higher pricing is pulling capital back into the class, but it is choosy. Programmes with good data, real voyage controls and sensible aggregate limits are getting placed. Broad annual covers with fuzzy Gulf exposure are not.
With a representative office in Dubai, this is a class where we think local knowledge and quick answers count for more than the size of the line.